empty
05.10.2026 12:00 PM
US dollar: markets push Fed hike bets to December

The September jobs report published on Friday shattered illusions about the strength of the US labor market. The economy added just 29k payrolls versus an 84k consensus, while July and August statistics were revised down a cumulative 60k. Average hourly earnings rose by only $0.05 (+0.1% m/m), and the annual pace slowed to 3.0%.

The market reaction was predictable: equity futures rallied, and Treasury yields fell. Markets interpreted the weak prints as meaning the Fed will refrain from hiking in October.

Fed officials were active last week, but unanimity is lacking. On September 29, Vice Chair John Williams said at the University at Buffalo there is "no need to rush" further rate increases. He implied that the Fed has time to assess incoming data and that an additional hike "later this year" could be appropriate. Michael Barr said policy adjustment is still required, and New York Fed President Austan Goolsbee wants evidence of cooling inflation, while Lisa Cook sees no signs of deceleration in price pressures.

This image is no longer relevant

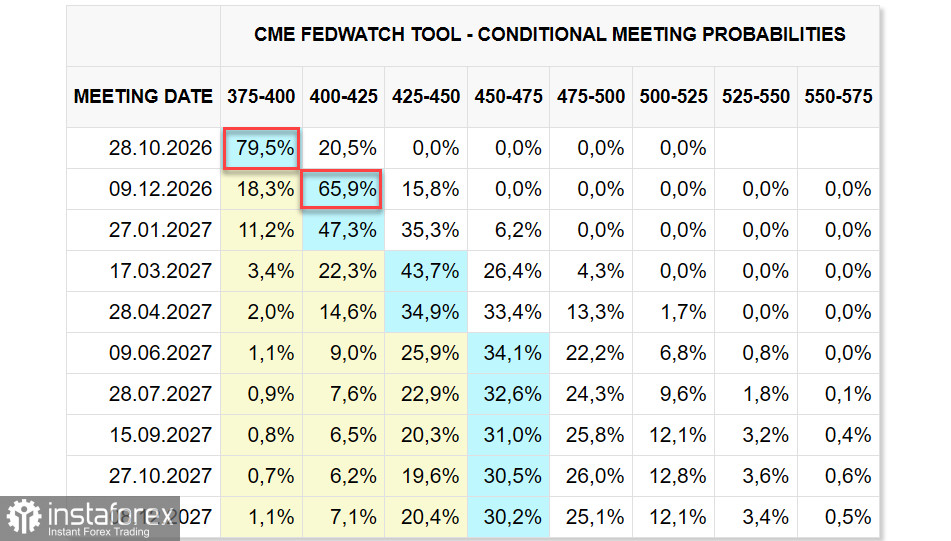
As a result, the base case shifted to a December hike, though October is not fully ruled out. For the dollar, that is clearly a bearish signal — but not a very strong one, since market participants had already suspected that some of Warsh's hawkish bravado was not fully supported by incoming data.

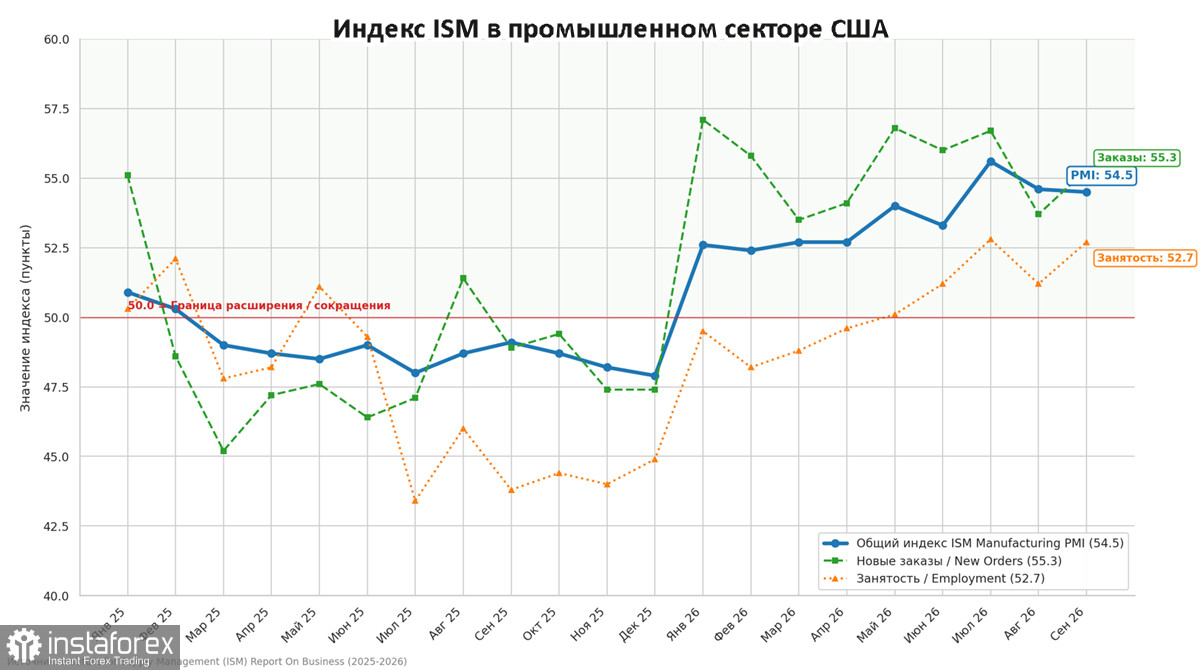
Other data is mixed and does not provide a clear picture. ISM manufacturing for September printed 54.5, just under August's 54.6, but new orders and employment showed gains. Crucially, the ISM prices-paid component jumped to 77.9 from 71.1 in August, a high not seen since May.

This image is no longer relevant

The Fed's preferred inflation gauge, core PCE for August, came in slightly below forecasts: +0.2% m/m (vs. +0.3% expected), with a 3.0% y/y rate. That is still far from the 2% target, but the absence of an acceleration again gives arguments in favor of an October pause.

Overall, the setup for the US dollar looks less bullish, and one might expect some short-term softening. However, recent CFTC data argues otherwise. Net long dollar positioning versus major currencies rose by $5.7bn to $24.1bn, a confident increase that shows speculators are still betting on USD strength.

This view makes sense if one assumes the US has little incentive to resolve the Iran conflict quickly: nearly everyone suffers from the situation except the US, which benefits as a reliable LNG supplier to Europe amid constrained and irregular deliveries. In absolute terms, the gain is limited, but the inflation threat and growth slowdown across major economies (excluding the US) persist and intensify. In that scenario, demand for dollars is unlikely to fall substantially.

We therefore assume that the dollar may modestly correct against commodity currencies in the short term, but European currencies face greater downside risk, and in the medium term, the dollar should remain well supported regardless of the Fed's October decision.

Kuvat Raharjo,
Analytical expert of InstaForex
© 2007-2026
Earn on cryptocurrency rate changes with InstaForex
Download MetaTrader 4 and open your first trade
  • Grand Choice
    Contest by
    InstaForex
    InstaForex always strives to help you
    fulfill your biggest dreams.
    JOIN CONTEST
  • Chancy Deposit
    Deposit your account with $3,000 and get $1000 more!
    In October we raffle $1000 within the Chancy Deposit campaign!
    Get a chance to win by depositing $3,000 to a trading account. Having fulfilled this condition, you become a campaign participant.
    JOIN CONTEST
  • Trade Wise, Win Device
    Top up your account with at least $500, sign up for the contest, and get a chance to win mobile devices.
    JOIN CONTEST
  • 30% Bonus
    Receive a 30% bonus every time you top up your account
    GET BONUS

Recommended Stories

Can't speak right now?
Ask your question in the chat.
Widget callback